


This is Part 4, the final part of a four-part series on the semi-truck parking business. In Part 1, we talked about what this business is and why the demand exists. In Part 2, we talked about how to pick a location. In Part 3, we talked about zoning, approvals, and what it costs to build one of these things.
Now let's talk about the part everybody wants to know about: what these things can actually earn, what they're like to operate, what happens when you sell, and why I've still been pretty cautious about jumping into this myself.
What do these things actually earn?
This is where the business starts to get interesting, because on one hand, the math is very simple.
You have a certain number of parking spaces. Each space rents for some amount per month. You subtract vacancy, expenses, and debt service, and whatever is left is your cash flow.
Pretty straightforward.
But the hard part is knowing whether your assumptions are actually right, because this is still a pretty immature business compared to something like self-storage, apartments, or mobile home parks.
There just aren't a ton of clean comps out there.
So before I show you the actual deals I looked at, let me explain the basic math, because if you understand these terms, you can look at almost any truck parking deal and get a rough idea of whether it can work.
- Gross rent is all the money coming in before anything gets subtracted. If you have 100 spaces renting for $150 per month, your gross parking rent is $15,000 per month.
- Vacancy is the allowance you make for spaces that aren't rented. I usually use 10 percent, which basically means I'm assuming one out of every ten spaces is empty at any given time.
- Operating expenses are the costs of running the property before debt service. Things like taxes, insurance, software, maintenance, repairs, snow removal if you're in a northern market, weed control, camera service, gate repairs, and the occasional cleanup.
- Net operating income, or NOI, is what's left after you pay those operating expenses, but before you pay the mortgage. Investors care about this number because it shows what the property itself is producing.
- Cap rate is the NOI divided by the purchase price. So if a property costs $500,000 and produces $50,000 per year in NOI, that's a 10 percent cap rate.
- Cash-on-cash return is the annual cash flow after debt service divided by the actual cash you put into the deal. So if you put $200,000 down and the property pays you $26,000 per year after the mortgage, that's a 13 percent cash-on-cash return.
Now, if you're not a numbers person, don't let all that scare you. The basic model is just this:
Take the number of spaces, multiply it by the monthly rent, add any building rent if the property has a building, subtract vacancy, subtract expenses, and then subtract the loan payment.
That's the whole thing.
For operating expenses, a rough number I've used is around 30 percent of gross revenue. One operator I talked to uses that same general rule. He wants all expenses to stay at or below 30 percent of gross income, and if the numbers don't work with that assumption, he gets pretty cautious.
For vacancy, I usually use 10 percent.
And for rent, monthly truck parking can vary widely. In weaker markets, you might see something like $100 to $150 per month per space. In stronger markets, especially where parking is really scarce, you might see $200, $250, or even $300 per month.
One real-world data point I saw near Atlanta was $275 per month for a 12-by-75 space. Another one in Smyrna, TN was $300 per month for a 12-by-70 space. And in my market here in Michigan, I've seen rates around $150 per month.
So, if you're just doing rough napkin math, $150 per month is probably a conservative starting point in a lot of places, but the local market really matters, because the number could be a lot higher.
Four deals I actually underwrote
Here are four real deals I looked at here in Michigan.
Just so we're clear, I passed on all of these. Some were too small. Some had zoning issues. Some had building problems. Some had price issues. But the numbers are still useful because they show how this business can work on paper.
| Deal | Spaces | Rent per space | Building income | Purchase price | NOI | Cash-on-cash | Cap rate |
|---|---|---|---|---|---|---|---|
| Barney Ave | 60 | $129/mo | $4,000/mo | $725,000 | ~$88,700 | 13% | 12% |
| Busha Hwy | 35 growing to 155 | $150/mo | $2,000/mo | $800K plus ~$695K build | ~$204,500 | 30% | ~34% on cost |
| Dixie Hwy | 80 | $129/mo | $8,000/mo | $600,000 | ~$138,500 | 54% | 23% |
| US-12 | 120 | $129/mo | $4,000/mo | $1,300,000 | ~$147,300 | 15% | 11% |
Now, look at that Dixie Highway deal for a second.
A 54 percent cash-on-cash return is kind of ridiculous. If you saw that number in a normal real estate deal, your first instinct should probably be, “Okay, what's wrong with it?”
And in this case, the thing driving that number was not the parking.
It was the building.
The property had a big building that could potentially produce around $8,000 per month in rent, and the purchase price was only $600,000. So yes, the truck parking helped, but the building was doing a huge amount of the heavy lifting.
That's one of the biggest lessons I learned from running these numbers.
A lot of the time, the building carries the deal.
The parking lot may be the exciting part, because that's the new business model we're talking about, but the building can be what makes the bank comfortable. It can produce the baseline income and give the property a more obvious use if the truck parking plan doesn't work. And it can be what makes the whole thing financeable.
This is one more reason I like properties that already have a structure on them.
Not because I want to deal with buildings. Frankly, I don't.
But if the building produces income (say, by leasing it to a third-party tenant, one who doesn't mind operating next to a truck parking lot), supports the zoning story, and gives the bank something they understand, it can make the whole deal a lot easier for the bank to digest.
The rent per square foot is not impressive
Now here's the honest downside.
If you compare truck parking to self-storage on a rent-per-square-foot basis, truck parking looks terrible.
A 20-by-80 truck parking space is 1,600 square feet. If that space rents for $129 per month, that's about eight cents per square foot per month.
Self-storage might rent for around a dollar per square foot per month, depending on the market.
So if all you're asking is, “Which business gets more rent per square foot?” self-storage wins by a mile.
But that's not really the right comparison, because the land, the construction, and the operating model are totally different.
Truck parking works because the land can be cheaper. The improvements can be simpler. The expenses can be lower. And in some markets, you may be one of the only legal, convenient options.
So the rent per square foot is not the magic.
The spread is the magic.
Can you buy or lease the dirt cheaply enough, improve it cheaply enough, and rent the spaces for enough to make the return worth the risk?
That's the question.
What return would I want?
Personally, I would want to see at least a 10 percent cap rate before I got serious about one of these.
And even that might not be enough if there are big unknowns with zoning, lease-up, paving requirements, drainage, or demand.
Some investors would probably be fine with a 7 or 8 percent cap rate, especially if the property is in a great location and they think the IOS market will keep getting stronger.
That's fine. I'm not necessarily saying they're wrong.
I'm just saying that for me, because this is still an immature market with limited comps and limited financing history, I would want to be paid for that uncertainty.
If I'm going to take on a weird property, in a weird niche, with a use that a lot of banks and municipalities still don't fully understand, I want the numbers to be pretty darn good.
Financing can be harder than you think
This is another place where the lack of data comes back to bite you.
A lot of banks have never underwritten a semi-truck parking facility.
They understand warehouses. They understand self-storage. They understand apartments. They understand a building with a tenant on a lease.
But a fenced gravel lot with a bunch of month-to-month truck drivers paying for parking? That's going to raise some eyebrows.
This is why local community banks are probably your best bet, especially if the property has a building, established income, and some kind of alternate use.
A bare gravel lot is much harder, because if the borrower defaults, what does the bank really have? They have a piece of land with a fence and gravel. That may be valuable to another truck parking operator, but it may not be valuable to the average buyer.
So the appraisal can become a problem. The loan amount can become a problem. The bank's comfort level can become a problem.
An SBA 504 loan may be an option in some situations, especially if there's a building or owner-occupied business use involved (assuming you plan to buy the property and equipment, rather than leasing it), but again, this is one of those things you'd want to run by a lender who actually understands SBA 504 loans (and believe me, many of them don't).
I'm not a lender or a CPA, and this is not financial advice. I'm just telling you how I would expect the conversation to go.
What it's actually like to run one
Once a monthly truck parking lot is built, approved, marketed, and full, the operation itself seems pretty simple.
That's actually one of the things that got me interested in this in the first place.
Compared to self-storage, there are fewer moving parts. No unit doors. No roll-up doors to repair. No locks to cut off. No hallways. No climate control. No tenant leaving a storage unit full of junk that you have to clean out.
It's basically outdoor parking with a gate, a payment system, and some rules.
That doesn't mean there are no problems. There are always problems. But the day-to-day work seems pretty light if the site is set up correctly.
A tenant signs up online, enters their information, uploads the documents you require, adds a payment method, and gets a gate code.
If you're using the right software, this can all happen without you personally talking to them.
Some operators use self-storage software and treat truck parking tenants like RV or boat storage tenants. Others use truck-parking-specific tools. Truck Parking Club also has a light dashboard if you're using them as a marketplace.
RELATED: 194: Truck Yeah! How Evan Shelley Makes Bank on Truck Parking Lots
The basic workflow is pretty simple:
- The tenant signs up.
- They agree to your parking rules.
- They enter a payment method.
- They get access to the gate.
- They park in their assigned spot.
- If they stop paying, the system flags them.
For a stabilized lot that rents spaces by the month (not by the hour or day), I've heard time estimates under five hours per week. In some cases, maybe under five hours per month.
That sounds almost too good to be true, and I'm sure the answer depends on the property, the tenants, the weather, the gate, the software, and how much nonsense people create.
But compared to most real estate businesses, it's pretty light.
You still need somebody local
I do think you can own one of these from a distance.
But like a self-storage business, I wouldn't want to own one without a local person who can stop by when needed.
That person doesn't necessarily have to be an employee. It could be a contractor, a maintenance person, a site manager, or somebody you trust who lives nearby.
But somebody needs to be able to:
- Check the lot occasionally
- Pick up trash
- Look at the gate if it stops working
- Make sure people are parking where they should
- Deal with snow or weeds depending on the market
- Meet a contractor if something needs to be fixed
The gate is probably the big one. If the gate breaks and a driver has a refrigerated trailer full of product sitting behind it, that becomes a problem immediately.
So, whether you own one of these locally or remotely, a gate repair plan is critical. You need somebody local who can get there fast. And ideally, there should be a backup way for tenants to get in and out if the system fails.
Security is partly real and partly perception
This was an interesting point that came up in my conversations with operators.
Tenants absolutely care about security. They want a fence. They want a gate. They want cameras. They want lighting. They want to feel like their equipment is safer on your lot than it would be behind a Walmart or on the side of the road.
And all of that stuff does help. But it doesn't make the lot bulletproof.
Somebody who really wants to get in can cut a fence. They can damage a gate. They can steal fuel or catalytic converters or break into a truck if they really want to.
So part of security is the actual protection, and part of it is the feeling of safety.
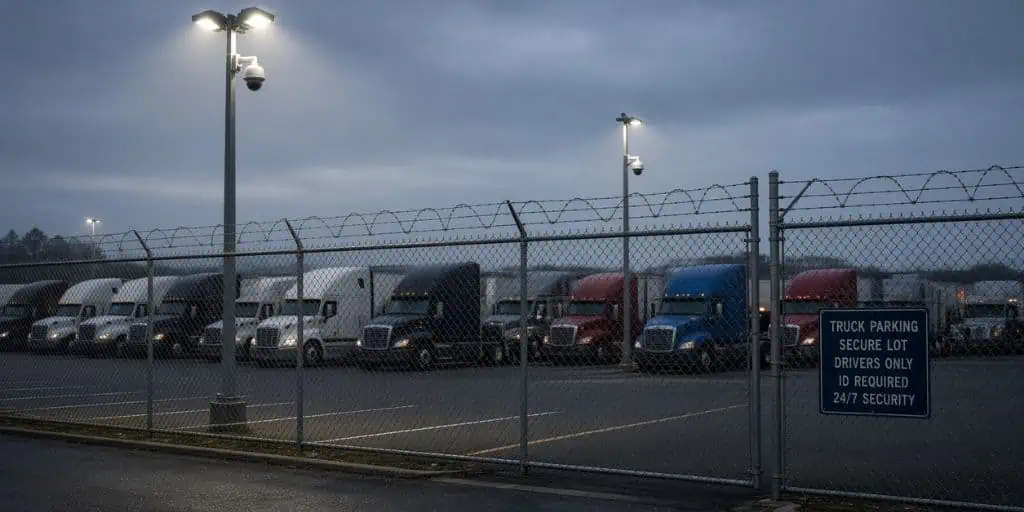
Security cameras may help deter bad behavior, but they also help you manage the property. They show who is parking crooked. They show when people are coming and going. They show if a turn is too tight and trucks keep clipping the same spot. They show if somebody dumped tires or oil containers near the fence.
In some ways, the cameras are less about catching criminals and more about understanding what's happening on the lot when you're not there.
And just so we're clear, you still want tenants carrying their own insurance. Their truck is their property, their cargo is their problem, and your lease agreement needs to spell that out.
Getting paid can become a legal issue
Collecting rent sounds easy until somebody stops paying and their truck is sitting inside your gate.
Mechanically, shutting off a gate code is easy.
Legally, it's not always that simple.
A semi-truck is titled personal property. It's not the same as a couch sitting inside a self-storage unit. If you trap somebody's truck without following the right process, you could create a much bigger problem for yourself.
In some states, self-storage lien laws may cover outdoor vehicle storage. In other states, they may not. Some states have special rules for titled vehicles. Some require specific notices, waiting periods, lienholder searches, and public sale procedures.
So I would not wing this.
You need a real parking agreement drafted for your state. It should cover the lien, default, access denial, towing rights, tenant insurance, abandonment, notices, and whatever else your attorney says needs to be in there.
I'm not an attorney, and this is definitely not legal advice. This is one of those places where being cheap up front could get really expensive later.
Abandoned trucks are a headache
Every now and then, somebody may stop paying and just leave the truck or trailer sitting there.
You can't just sell it. You can't just scrap it. You can't just say, “Well, I guess it's mine now.”
In most states, you're dealing with some version of a storage lien or towing lien process. That usually means documenting the vehicle, pulling the title record from the DMV, notifying the owner and any lienholder, waiting through a redemption period, advertising the sale, and then selling it through the proper process.
A heavy tow can cost a thousand bucks or more. Sometimes a lot more.
And depending on the state, there may be limits on how much of your unpaid rent or storage fees you can actually recover.
So this isn't necessarily a disaster, but it's not nothing either. It's one of those operational headaches you need to plan for in the lease and in your procedures before it happens.
Scaling up and selling a parking lot
One reason I like this business is that it seems pretty scalable if you keep the model simple.
I'm not talking about nightly parking with showers, bathrooms, food, security guards, and people calling at two in the morning because they can't get in.
I'm talking about monthly parking. A very similar concept to a self-storage facility.
If the lots are set up well, and you have software, cameras, gate access, local help, and a clear process for late payments and rule violations, one person could probably run several of these without it becoming a full-time job.
One operator estimate that stuck with me was that a person with good systems and local help could realistically run five to ten lots at maybe 20 hours per week total.
That sounds believable to me, assuming the lots are stable and not constantly breaking.
Clustering seems to be the smarter way to grow
One thing I noticed when studying larger operators is that they don't always spread out evenly across the map. They cluster.
Instead of opening one lot in ten different cities, they might open three, four, or five lots around the same major highway exit or industrial area, which makes a lot of sense.
If one interchange has real demand, the second lot nearby may be easier to fill than a totally new lot in a totally new city. The same Google presence can help. The same local manager can help. The same contractor can help. The same market knowledge carries over.
So if your first lot fills up quickly, the next opportunity may not be 200 miles away.
It may be a mile down the road.
The exit depends on whether you own the real estate
This was one of the biggest questions I had early on.
If you build one of these and it works, who buys it?
The answer depends a lot on whether you own the dirt.
Some operators don't. They lease a lot from a property owner and then sublease the spaces to truck drivers. That's a legitimate way to start because it takes far less capital and risk. You don't need to buy the land. You just need to control it with a lease and create the spread between what you pay the landlord and what your tenants pay you.
But when you sell that, you're selling a business.
You're selling cash flow, systems, tenant relationships, and maybe a valuable lease if the terms are good and assignable.
That's not worthless, but it's different from selling real estate.
If you own the land, you're selling into the industrial outdoor storage market, or IOS.
That's a much bigger, more established buyer pool. Institutional buyers understand industrial land. They understand outdoor storage. They understand truck terminals, trailer parking, container storage, and contractor yards.
So even if your use is semi-truck parking, the buyer may not think of it as a truck parking deal. They may think of it as an IOS deal, which is an important distinction.
The best operating setup may not be the best exit setup
If you're running the business for cash flow, a parking lot full of month-to-month owner-operators can be great. You have lots of small tenants, which means no single tenant controls your income. If one driver leaves, it's not a big deal.
That feels safe from an operations standpoint, but institutional buyers often see it differently.
They may see 100 small tenants on short leases and view that as less secure than one big tenant with strong credit on a long-term lease.
So a site leased to Amazon, FedEx, UPS, or some other large credit tenant for three to ten years may sell at a better cap rate than a lot full of individual drivers, even if the day-to-day income from the smaller tenants feels more diversified.
That's kind of the weird twist.
The tenant mix that helps you sleep at night as an operator may not be the tenant mix that gets you the highest sale price.
And one operator said something else that stuck with me:
“Sometimes no tenant is better than a bad long-term tenant.”
In other words, if you sign a ten-year lease at a low rent, you may have locked away the upside. A buyer might look at that and say, “Well, I'd love the property, but I'm stuck with this cheap lease for the next decade.”
An empty site at least gives the next buyer optionality.
So if your long-term plan is to sell to an institutional IOS buyer, you should start thinking about that early. The lease terms you sign today can affect the buyer pool years from now.
Portfolios usually get more attention than one-off sites
Institutional buyers can and do buy one site at a time.
But like most real estate businesses, you usually get more attention if you have a small portfolio of good locations.
A buyer would rather buy five strong sites in one transaction than chase five separate sellers for five separate deals.
That doesn't mean you need a giant portfolio to have an exit. It just means that scale can create a premium if the sites are good, the income is clean, and the locations make sense.
In the right markets, IOS sites can trade for a few million dollars per acre, but I would be very careful about throwing out any broad cap rate or valuation number, because this market moves and the details matter a lot.
If you're trying to figure out what these are selling for today, I would look at Crexi, LoopNet, CoStar (if you have access), and actual IOS broker reports. I wouldn't rely on a number in a blog post, including this one, because by the time you read it, the market could have changed.
The stuff nobody tells you
This is the part I think is really important, because a lot of the content I've seen about this business makes it sound way easier than it is.
The pitch usually goes something like this:
Find a building with an empty parking lot, lease the lot from the owner, rent the spaces to truckers, and collect checks.
And in the most basic sense, yes, that's the idea.
But that explanation skips over a ton of steps.
- How do you find the owner?
- How do you make the offer?
- How do you write the lease?
- Does the lease allow subleasing?
- Who carries the insurance?
- Who is responsible for the fence, gate, lights, cameras, gravel, drainage, signage, snow removal, trash, and repairs?
- Does the zoning allow truck parking?
- Can trucks actually turn into the driveway?
- How do drivers find you?
- What happens when somebody doesn't pay?
- What happens when somebody abandons a trailer?
- What happens when the gate breaks?
- What happens when the city gets a complaint?
Those are not tiny details; they're the entire business!
So when somebody explains this in two steps, just understand that they're leaving out the ninety-eight other steps that make it actually work.
The biggest mistake is spending real money before you've verified the deal.
This business is not hard to understand, but it is very easy to get wrong.
And it's easy to get wrong because the information isn't sitting out there neatly organized for you.
In self-storage, you can pay for a feasibility study. You can get competitor data. You can look at square footage per capita. You can see rent comps. You can get a much clearer idea of whether the market is overbuilt or underserved.
With truck parking, you're usually piecing it together yourself.
You need to call trucking companies. You need to look at FMCSA data or tools like CarrierSource. You need to check state DOT truck counts. You need to read local parking ordinances. You need to call existing facilities. You need to ask whether they're full. You need to understand what drivers are paying and what they actually need.
That's a lot of work (although I should point out that this work is getting substantially easier with tools like Claude Code).
And because it's a lot of work, a lot of people won't do it.
They'll just buy the property, assume the demand is there, and hope the trucks show up.
Maybe they will.
But I wouldn't bet a million bucks on maybe.
Be careful with optimistic rent assumptions.
This is another trap.
During the 2021 market, when real estate was going crazy and money was cheap, a lot of deals only made sense if you assumed rents would rise dramatically.
Maybe the current rent was $150 per month, but the spreadsheet assumed it would be $250 next year.
Could that happen? Sure, maybe.
But if the deal only works after a huge rent increase, then the deal doesn't really work today.
One operator I talked to was looking at truck parking deals during that period and just couldn't get comfortable with the numbers. Everything depended on future rent growth, and he didn't want to build a business around that assumption.
I think that's the right instinct.
Underwrite today's rent. If the rent goes up later, great. That's extra icing on the cake. But don't make the deal depend on it.
The lease-up question is still fuzzy.
One question I still don't have a clean benchmark for is how long it should take a brand-new truck parking lot to fill up.
In self-storage, a new facility might take two to three years to stabilize.
Truck parking seems like it can be much faster in a good market, because the demand already exists and the problem is mostly awareness. Drivers need to know you're there. They need to trust the lot. They need to understand the price. They need to know how to sign up.
Keith Cristal said his first lot filled in about two months, and he once had a location that filled up in one week.
Evan Shelley said some locations on Truck Parking Club start getting bookings the same day they're onboarded, sometimes within hours.
That's amazing… but those are also anecdotes. Not a clean industry benchmark.
So, if I were underwriting one of these, I would probably be conservative and assume it could take a solid year to lease up, unless I had really strong evidence that the demand was already sitting there waiting.
And again, that's where the pre-marketing matters. If you already have a list of nearby carriers, and you've already talked to drivers, and you already know people are actively looking for parking, you can be a lot more confident than somebody who just opens the gate and hopes.
Why I'm still moving slowly
At this point, you might be wondering, if I think this is such a good opportunity, why don't you have twenty locations by now?
Fair question. And I think there are really two answers.
The first one is capital.
This is not like buying cheap vacant land for a thousand bucks. That's how I got started in real estate, and the beauty of that business was that I could make mistakes without blowing myself up.
Truck parking is different.
If you're buying an industrial property, or developing a lot, or even leasing a site and putting real money into improvements, you can get into six or seven figures pretty quickly.
It's a different kind of risk. And like many real estate investors I know, my income sources have slowed down over the past year, so I haven't had the same war chest sitting there ready to deploy into a new, weird business model.
The second reason is the data gap.
I like data. I like comps. I like benchmarks. I like being able to look at a market and say, “Okay, here's the supply, here's the demand, here's what competitors are charging, here's how full they are, and here's how long this should take to lease up.”
With truck parking, a lot of that doesn't exist yet. And that is both the opportunity and the problem.
The opportunity is that most people are scared away by the missing data, which means the competition is lower.
The problem is that the missing data also makes it harder to write a big check with confidence.
This is one of those weird situations where the exact thing that makes the business attractive is also what makes it uncomfortable.
I do think this is a genuinely interesting opportunity.
I think the demand is real. I think the business model is simpler than most. I think the operations can be very manageable. And I think there are still markets where a smart person could find a property nobody else knows what to do with and turn it into a nice little cash-flowing asset.
But I also think you have to make the decision very carefully.
You can't just buy land because it's cheap.
You can't just assume every truck driver nearby will become your tenant.
You can't just trust the zoning because somebody told you it should be fine.
You can't just assume the city will let you build a gravel lot.
And you definitely can't let a pretty spreadsheet talk you into ignoring all those questions.
So if I had to boil down my own conclusion, it would be this:
This business is probably not that hard to run once it's working.
The hard part is everything before that.
Finding the right market. Finding the right property. Confirming the use is legal. Making sure trucks can physically use the site. Pricing it correctly. Building only what needs to be built. Getting the drivers to know you exist. And doing all of that without overpaying.
If you can get those decisions right, I think this can be a really really good business.
If you get them wrong, it can become a very expensive pile of gravel.
I'm not necessarily telling you that you should or shouldn't go chase this. I'm just sharing how I'm thinking through it after a year of studying it, talking to operators, running real numbers, and looking at actual properties.
For the right person, with the right market, the right capital, and the willingness to do the uncomfortable homework, I think this is one of the more interesting real estate niches I've seen in a long time.
And if nothing else, I can tell you this much: once you understand the problem, you'll never look at a semi-truck parked behind a Walmart the same way again.
That's the whole series! If you want to start from the beginning, head back to Part 1 here.


The biggest takeaway for me is that truck parking looks simple on the surface, but the real business is in the homework before opening the gate. The point about underwriting today’s rent instead of relying on future rent increases really stood out. I also found the distinction between operating a monthly parking business and creating an attractive IOS asset for a future buyer very interesting. The lack of reliable market data seems to be both the biggest challenge and one of the biggest opportunities in this niche.